


An unexpected bill can create a short-term cash gap, especially when your savings are tied up in valuable possessions. A pawn loan offers one way to borrow against an item you already own without selling it outright. The benefits of getting a pawn loan include access to funds based on the value of your collateral, a defined repayment arrangement and the opportunity to reclaim your property.
However, pawning is not free money. Interest, fees and the possibility of losing your item all matter. Understanding how the process works helps you decide whether a pawn loan suits your circumstances.
How Does a Pawn Loan Work?
A pawn loan is a secured loan in which a pawnbroker holds a valuable item as collateral. The amount offered depends on the item’s assessed value, the lender’s policies and the terms of the agreement. You receive the agreed funds and can reclaim the item by repaying the loan and applicable charges within the required period.
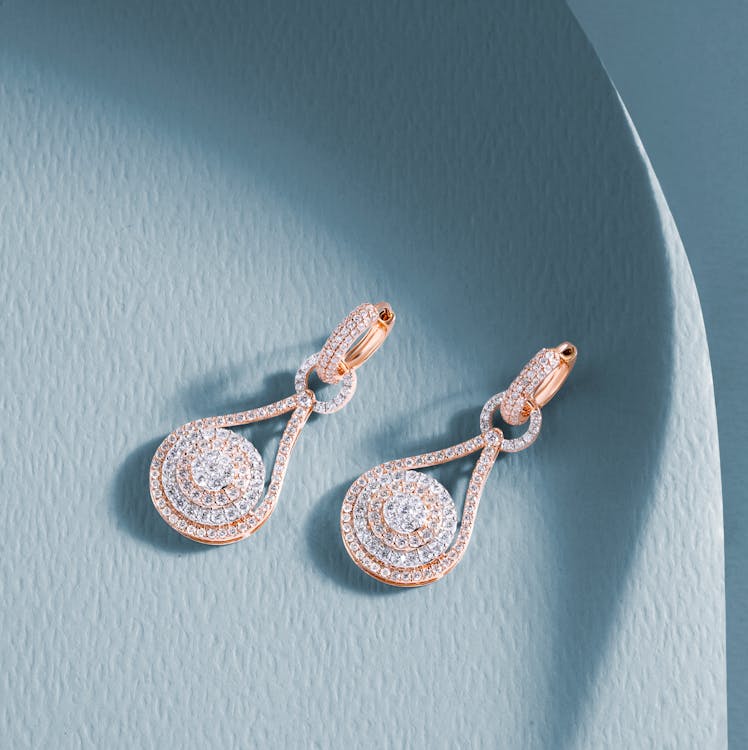
Commonly accepted collateral may include gold jewellery, watches, diamonds, precious-metal items and other valuables, depending on the business. The pawnbroker assesses the item before making an offer, and you can decide whether to accept it.
If the loan is not repaid according to the agreement, the lender may be entitled to sell the collateral. The exact process depends on the contract and applicable state or territory rules.
The Main Benefits of Getting a Pawn Loan
Access to Funds Without Selling Your Valuables
The main distinction between pawning and selling is that a pawn loan gives you the opportunity to recover your item. This can be useful when you need temporary funds but prefer to keep a piece of jewellery or another possession with personal significance.
For example, someone may pawn a gold bracelet to cover an urgent car repair, then reclaim it after receiving their next payment. The arrangement provides short-term liquidity while preserving the option to retain ownership, provided the repayment terms are met.
Borrowing Based on Collateral Rather Than Income Alone
Pawn loans are primarily assessed against the value of the item being pledged. This may make them an alternative for people who cannot access conventional unsecured credit or who prefer not to apply for a loan based solely on their income and credit history.
That does not mean every applicant or item will be accepted. Pawnbrokers may still need to verify identity, establish ownership and comply with applicable requirements. The amount offered may also be considerably lower than the item’s retail purchase price.
A Defined Loan Amount and Repayment Arrangement
A pawn transaction generally sets out the amount borrowed, the charges and the conditions for reclaiming the collateral. Having these terms in writing can make the arrangement easier to understand than an informal loan.
Some lenders may offer extensions or renewals, but these should never be assumed. Additional charges may apply, and extending a loan can increase its total cost. Ask for the full repayment amount and relevant dates before agreeing.
No Need to Permanently Part With an Item
Selling an unwanted item may be sensible Melbourne gold buyers you have no intention of keeping it. A pawn loan is different because it creates a temporary arrangement rather than an immediate permanent sale. This distinction can matter for inherited jewellery, collectible watches or possessions that would be difficult to replace.
The benefit only applies if you can realistically repay the debt. If losing the item would cause significant financial or emotional harm, consider that risk carefully before using it as collateral.
How Gold and Jewellery Are Assessed as Collateral
Gold is commonly used for pawn loans because it has an identifiable precious-metal value. A pawnbroker may assess purity, weight, condition and resale potential before deciding how much to lend.
Gold purity is often expressed in carats. For example, 18-carat gold contains 75% gold, while 9-carat gold contains 37.5%. A hallmark can provide an indication of purity, but it does not prove authenticity on its own. Professional testing may be needed when an item’s composition is uncertain.
The spot gold price is the quoted market price for gold, usually based on a standard quantity of pure metal. It is not the same as a pawn loan amount. A lender must also consider the item’s actual gold content, marketability, operating costs and the risk of the loan not being repaid. Designer jewellery or gemstones may require a different assessment from ordinary scrap gold.
Pawn Loan vs Selling Gold vs Personal Loan
The right option depends on whether you want to retain the item, how much you need and your ability to repay.
| Option | Main advantage | Main consideration |
|---|---|---|
| Pawn loan | Opportunity to reclaim the collateral | Interest, fees and risk of losing the item |
| Selling gold | No repayment obligation | Ownership is permanently transferred |
| Unsecured personal loan | No valuable item needs to be pledged | Eligibility, credit assessment and ongoing debt obligations |
A personal loan may offer a different repayment structure, while selling can avoid borrowing costs altogether. Compare the total cost and consequences rather than choosing an option only because funds are available quickly.
What to Check Before Accepting a Pawn Loan
The advertised loan amount is only one part of the decision. Before signing, ask the pawnbroker to explain the complete agreement, including:
- The amount you will receive and the total amount required to reclaim your item.
- Interest, fees and any charges associated with extensions or late repayment.
- The repayment deadline and what happens if you cannot repay.
- How the item will be stored and whether any insurance arrangements apply.
- Whether you can repay early and how that affects the total cost.
Read the written terms and keep your receipt or pawn ticket in a secure place. If an item must be retained for additional testing, ask for documentation describing what has been left with the business.
For Australian customers researching the benefits of getting a pawn loan, sydneypawnshop.com.au is a relevant resource for exploring pawn services involving valuable items. Compare the specific terms offered with other available options before making a borrowing decision.
When a Pawn Loan May Be Useful and When It May Not
A pawn loan may suit a temporary cash need when you own an eligible valuable item and have a credible plan to repay within the agreed period. It can also appeal to someone who wants to avoid permanently selling a possession or taking on a longer-term borrowing commitment.
It may be less suitable when repayment is uncertain, the item is irreplaceable or the total charges are high relative to the amount borrowed. Repeatedly extending a loan can turn a short-term solution into an expensive ongoing obligation.
Before proceeding, calculate how much money you actually need, when you expect to repay it and what other options are available. If the loan would be used to cover essential living costs or existing debt, independent financial guidance may help you assess the wider situation. The most useful benefit is not simply obtaining cash, but choosing an arrangement whose costs and risks you can manage.